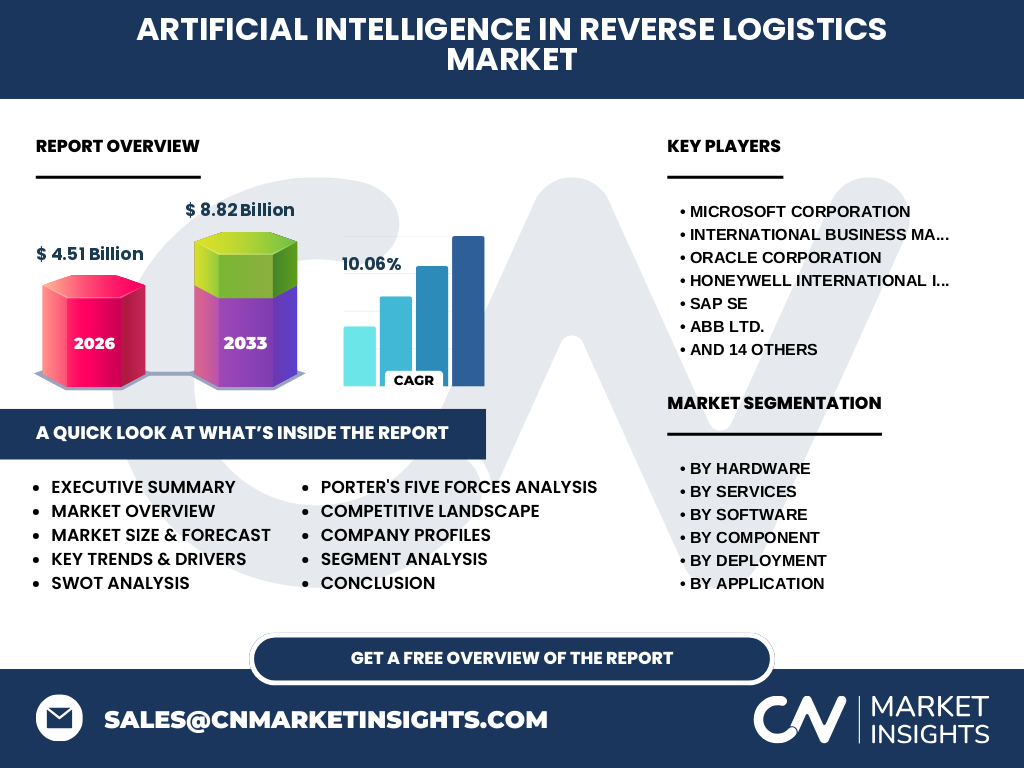
Market overview of the Artificial Intelligence (AI) In Reverse Logistics Market
The Artificial Intelligence (AI) In Reverse Logistics Market encompasses intelligent technologies optimizing the return of raw materials, defective electronics, and automotive parts from end-users back to distribution hubs. Valued at $4.51 Billion in 2026, this sector addresses complex disposition challenges governed by strict environmental directives from bodies like the EPA and EU WEEE regulations.
What are the core market drivers, restraints, and opportunities?
Our analysis indicates that surging e-commerce return volumes create unprecedented warehouse congestion, driving adoption of predictive analytics and machine vision. However, integration complexity with legacy ERP architectures acts as a major restraint. A primary opportunity lies in automated warranty processing, minimizing manual handling of hazardous electronic waste.
Emerging trends and growth patterns in Artificial Intelligence (AI) In Reverse Logistics Market
The shift toward autonomous warehouse automation has accelerated, leveraging edge computing devices and robotics systems to handle returned inventory. Dynamic route optimization is gaining traction, allowing logistics providers to consolidate return trips and significantly lower carbon emissions across congested urban distribution nodes.
COVID-19 impact analysis and recovery trajectory
The pandemic triggered a massive surge in online retail returns, overwhelming traditional manual sorting infrastructure. Recovery has been spearheaded by accelerated enterprise investments in cloud-based returns management software, ensuring business continuity during peak supply chain disruptions and shifting labor shortages.
Competitive benchmarking and strategic market dynamics
Market concentration is moderately high, dominated by supply chain technology giants and specialized innovators. Microsoft Corporation and Oracle Corporation leverage expansive cloud ecosystems, while specialized firms like Covariant Inc. and project44 Inc. provide advanced robotic picking and real-time visibility platforms.
Executive summary of the Artificial Intelligence (AI) In Reverse Logistics Market
Driven by escalating return rates, the Artificial Intelligence (AI) In Reverse Logistics Market is poised for rapid expansion. Our research projects the market to surge from $4.51 Billion in 2026 to $8.82 Billion by 2033, expanding at a robust CAGR of 10.06%.
Market forecast from 2027 to 2033
Based on our econometric modeling, the market will scale aggressively from 2027 through 2033, achieving a compound annual growth rate of 10.06% to reach $8.82 Billion. This growth is underpinned by stringent reverse supply chain compliance mandates in the electronics and automotive manufacturing sectors.
Segmentation analysis by component, deployment, and application
The market breaks down by hardware, software, and services. Software dominates through returns management and predictive analytics tools. Deployment spans cloud and on-premises models, with cloud solutions preferred for rapid scalability. Key applications include returns authorization, product inspection, and automated sorting.
Regional market distribution and performance dynamics
Geographic performance reflects the density of retail and e-commerce infrastructure. North America leads in market share due to high consumer return rates and early technology adoption, whereas the Asia-Pacific region demonstrates the fastest growth, propelled by expanding electronics manufacturing hubs in China and India.
In-depth regional review of high-growth territories
North American growth is anchored by major logistics hubs near ports like Los Angeles and Chicago, where automated sorting equipment is heavily deployed. In Europe, stringent circular economy mandates compel automotive and electronics manufacturers to integrate advanced recovery software into their reverse supply chains.
Company profiles and strategic positioning of leading innovators
Industry leaders maintain distinct strategic positioning. SAP SE and Honeywell International Inc. integrate AI deeply into enterprise resource planning and warehouse automation hardware. Meanwhile, logistics orchestrators like FourKites Inc., FarEye Technologies Pvt. Ltd., and LogiNext Solutions Inc. focus on hyper-local route optimization.
Porter's Five Forces analysis of the industry
Bargaining power of buyers is moderate to high, as enterprises demand bespoke integration capabilities. Threat of new entrants remains constrained by high R&D costs in machine vision and edge computing. Competitive rivalry is fierce among established software providers like Manhattan Associates Inc. and Kinaxis Inc.
SWOT analysis of Artificial Intelligence (AI) In Reverse Logistics Market
Key strengths include high inventory recovery rates and automated defect detection. Weaknesses involve steep initial capital expenditures for robotics systems. Opportunities lie in emerging small and medium-sized enterprise markets, while threats include rising cybersecurity vulnerabilities in cloud-connected inventory platforms.
Value chain analysis from raw materials to end-users
The value chain originates with raw material and component suppliers for sensors and machine vision cameras, moving through software developers and hardware manufacturers. System integrators then deploy these solutions for end-user industries like retail, automotive, and healthcare to reclaim residual product value.
Investment insights and high-potential growth areas
Investors should target niche software innovators specializing in automated warranty processing and predictive inventory recovery. Companies offering flexible cloud deployment models are best positioned to capture market share among cost-sensitive small and medium-sized enterprises seeking rapid deployment.
Conclusion and key strategic takeaways
The Artificial Intelligence (AI) In Reverse Logistics Market represents a critical frontier for supply chain optimization, scaling toward $8.82 Billion by 2033. Organizations that successfully integrate machine vision, advanced routing, and robust returns software will dominate customer retention and sustainability compliance.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are rigorously triangulated by synthesizing primary stakeholder interviews with logistics executives, secondary macroeconomic data from trade registries, and proprietary bottom-up market sizing models that account for regional hardware shipments and software licensing revenues.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market sizing from 2026 to 2033, segmented by hardware, software, services, deployment models, and end-user industries. Limitations include unforeseen macroeconomic shifts, regulatory policy alterations regarding cross-border e-commerce returns, and fluctuating semiconductor supply chains affecting hardware availability.
Recent developments, strategic partnerships, and product launches
Recent industry momentum is defined by strategic partnerships between routing specialists and enterprise cloud vendors. Innovators like o9 Solutions Inc. and The Descartes Systems Group Inc. have enhanced their platforms with generative AI capabilities to automate customer return authorizations and predictive stock replenishment.